
The scope of a KYC platform affects more than the checks it performs. It shapes where customer data is managed, how verification decisions are made, who is responsible for running the process, and how much friction customers encounter during verification. For businesses with established KYC workflows, choosing a new provider also means deciding which systems to retain, integrate, or replace.
In this guide, we compare five top KYC solution providers — Regula, Sumsub, Trulioo, Jumio, and Persona — to show what each offers and what to consider before making a choice.
What are the best KYC software providers in 2027, and how do they compare?
| Provider | Main focus | When to consider |
|---|---|---|
| Regula | High-assurance identity verification and configurable KYC and AML workflows | You need rigorous document and biometric checks for high-stakes onboarding, ongoing verification, and risk-based step-up checks. Seamless integration with third-party services and legacy systems is a priority. |
| Persona | Configurable KYC/KYB processes with additional fraud intelligence | You need to assess business credibility and connections between potentially fraudulent accounts alongside standard KYC checks |
| Trulioo | Global identity and business verification | You verify customers and businesses across countries and need access to different verification methods and local data sources |
| Sumsub | Broad KYC, KYB, and AML compliance | You want to manage identity verification and a wide range of financial crime compliance tasks through one provider. |
| Jumio | Identity verification and risk-based decisioning | You need identity checks and watchlist screening in a connected process, including alerts about changes in customer risk |
Regula
Regula is a strong fit for high-stakes KYC scenarios that demand rigorous identity verification. Its Regula IDV Platform combines advanced document authentication, facial biometrics, KYC/AML screening, and configurable verification workflows to support international customer onboarding, ongoing identity checks, and step-up verification.
For businesses onboarding customers across borders, document coverage can be a challenge. Regula supports more than 17,000 document templates from 254 countries and territories, including less common IDs. This helps its customers reduce verification dead ends caused by unsupported documents.
The depth of verification is another strength, backed by decades of forensic expertise. Its technology supports more than 50 document authenticity checks to detect signs of forgery and alteration. Combined with face matching and liveness detection, these checks help businesses spot sophisticated identity fraud. In recent independent testing, Regula's facial biometrics successfully rejected all 750 presentation attacks evaluated.
Regula also supports a risk-based approach to KYC. Teams can combine document and biometric checks with third-party services, including AML/PEP and adverse media screening, suspicious device and IP activity detection, and configure different verification paths based on risk signals.
A case management system allows you to review all flagged cases in one place and manage follow-up actions right in the platform, without switching between different interfaces.
Beyond onboarding, reusable customer profiles keep identity data and verification history in one place, reducing the need for returning customers to submit the same information again. Scheduled identity refreshes help keep these records up to date.
The platform supports customer-managed cloud and on-premises deployment and integrates with existing third-party and legacy systems.
In practice: iCard

Serving 1.4 million customers across more than 30 countries, European digital wallet provider iCard previously relied on manual identity checks, which caused delays, particularly outside business hours. The company also needed a faster way to verify customers when its risk assessment system flagged suspicious activity, such as the use of a new device.
With Regula's identity verification technology integrated into its KYC process, iCard automated document and biometric checks, reducing customer verification time to under one minute.
Persona
Persona provides KYC automation and business verification (KYB) software for verifying individuals and businesses, with a particular emphasis on configurable compliance and fraud prevention processes. Alongside document and biometric verification, database checks, and AML screening, its KYB tools help businesses verify company details and ultimate beneficial owners (UBOs).
Persona also offers ways to assess risks beyond standard identity and business checks. Its Online Credibility tools examine business websites, social media presence, and reviews, providing additional signals when traditional registry data is limited. Persona Graph helps identify potentially fraudulent accounts by analyzing shared attributes, such as device fingerprints, IP addresses, and contact details.
For businesses working with multiple partners, Persona Connect allows participating Persona customers to share KYC and KYB data and verification results with the end user's consent. Partners can reuse this information or run their own checks, reducing duplicate verification. The service is currently in beta.
Trulioo
Trulioo offers a global identity and business verification platform for companies onboarding customers across multiple markets. It combines document and biometric verification, electronic IDs, and identity checks against more than 450 global and local data sources. This gives businesses several ways to verify customers depending on the country, available identity data, and risk requirements.
Beyond individual KYC, Trulioo supports business verification, including company registration checks and UBO identification. Its UBO Discovery uses agentic AI and the Trulioo Business Graph to trace complex ownership structures across jurisdictions, even when registry data is incomplete. The platform also offers AML screening and ongoing watchlist monitoring.
Its Workflow Studio lets teams combine verification methods and configure conditional steps based on customer information and verification results.
Sumsub
Sumsub offers a broad KYC and compliance platform covering identity verification, AML screening, KYB, transaction monitoring, and fraud prevention. Its product range makes it relevant to businesses looking to manage multiple compliance processes through a single provider.
Beyond standard document and biometric checks, Sumsub supports non-document identity verification, proof of address, bank account verification, and device intelligence. AML screening checks customers against sanctions, PEP, and other risk lists, while transaction monitoring helps detect suspicious financial activity. For KYC in crypto businesses, Sumsub also offers tools for Travel Rule compliance.
Jumio
Jumio combines document and biometric identity verification with AML screening to support customer due diligence during onboarding and ongoing monitoring. Its KYC process includes ID capture, selfie matching, and liveness detection, alongside checks against sanctions, PEP, and adverse media lists.
Businesses can customize which watchlists to screen against and conduct additional checks for higher-risk customers. Jumio uses AI-powered matching designed to reduce false positives and manual reviews. For existing customers, ongoing AML monitoring generates alerts about potential new or changed screening matches, allowing compliance teams to investigate findings and update customer risk levels.
Which capabilities matter when comparing the best KYC solutions?
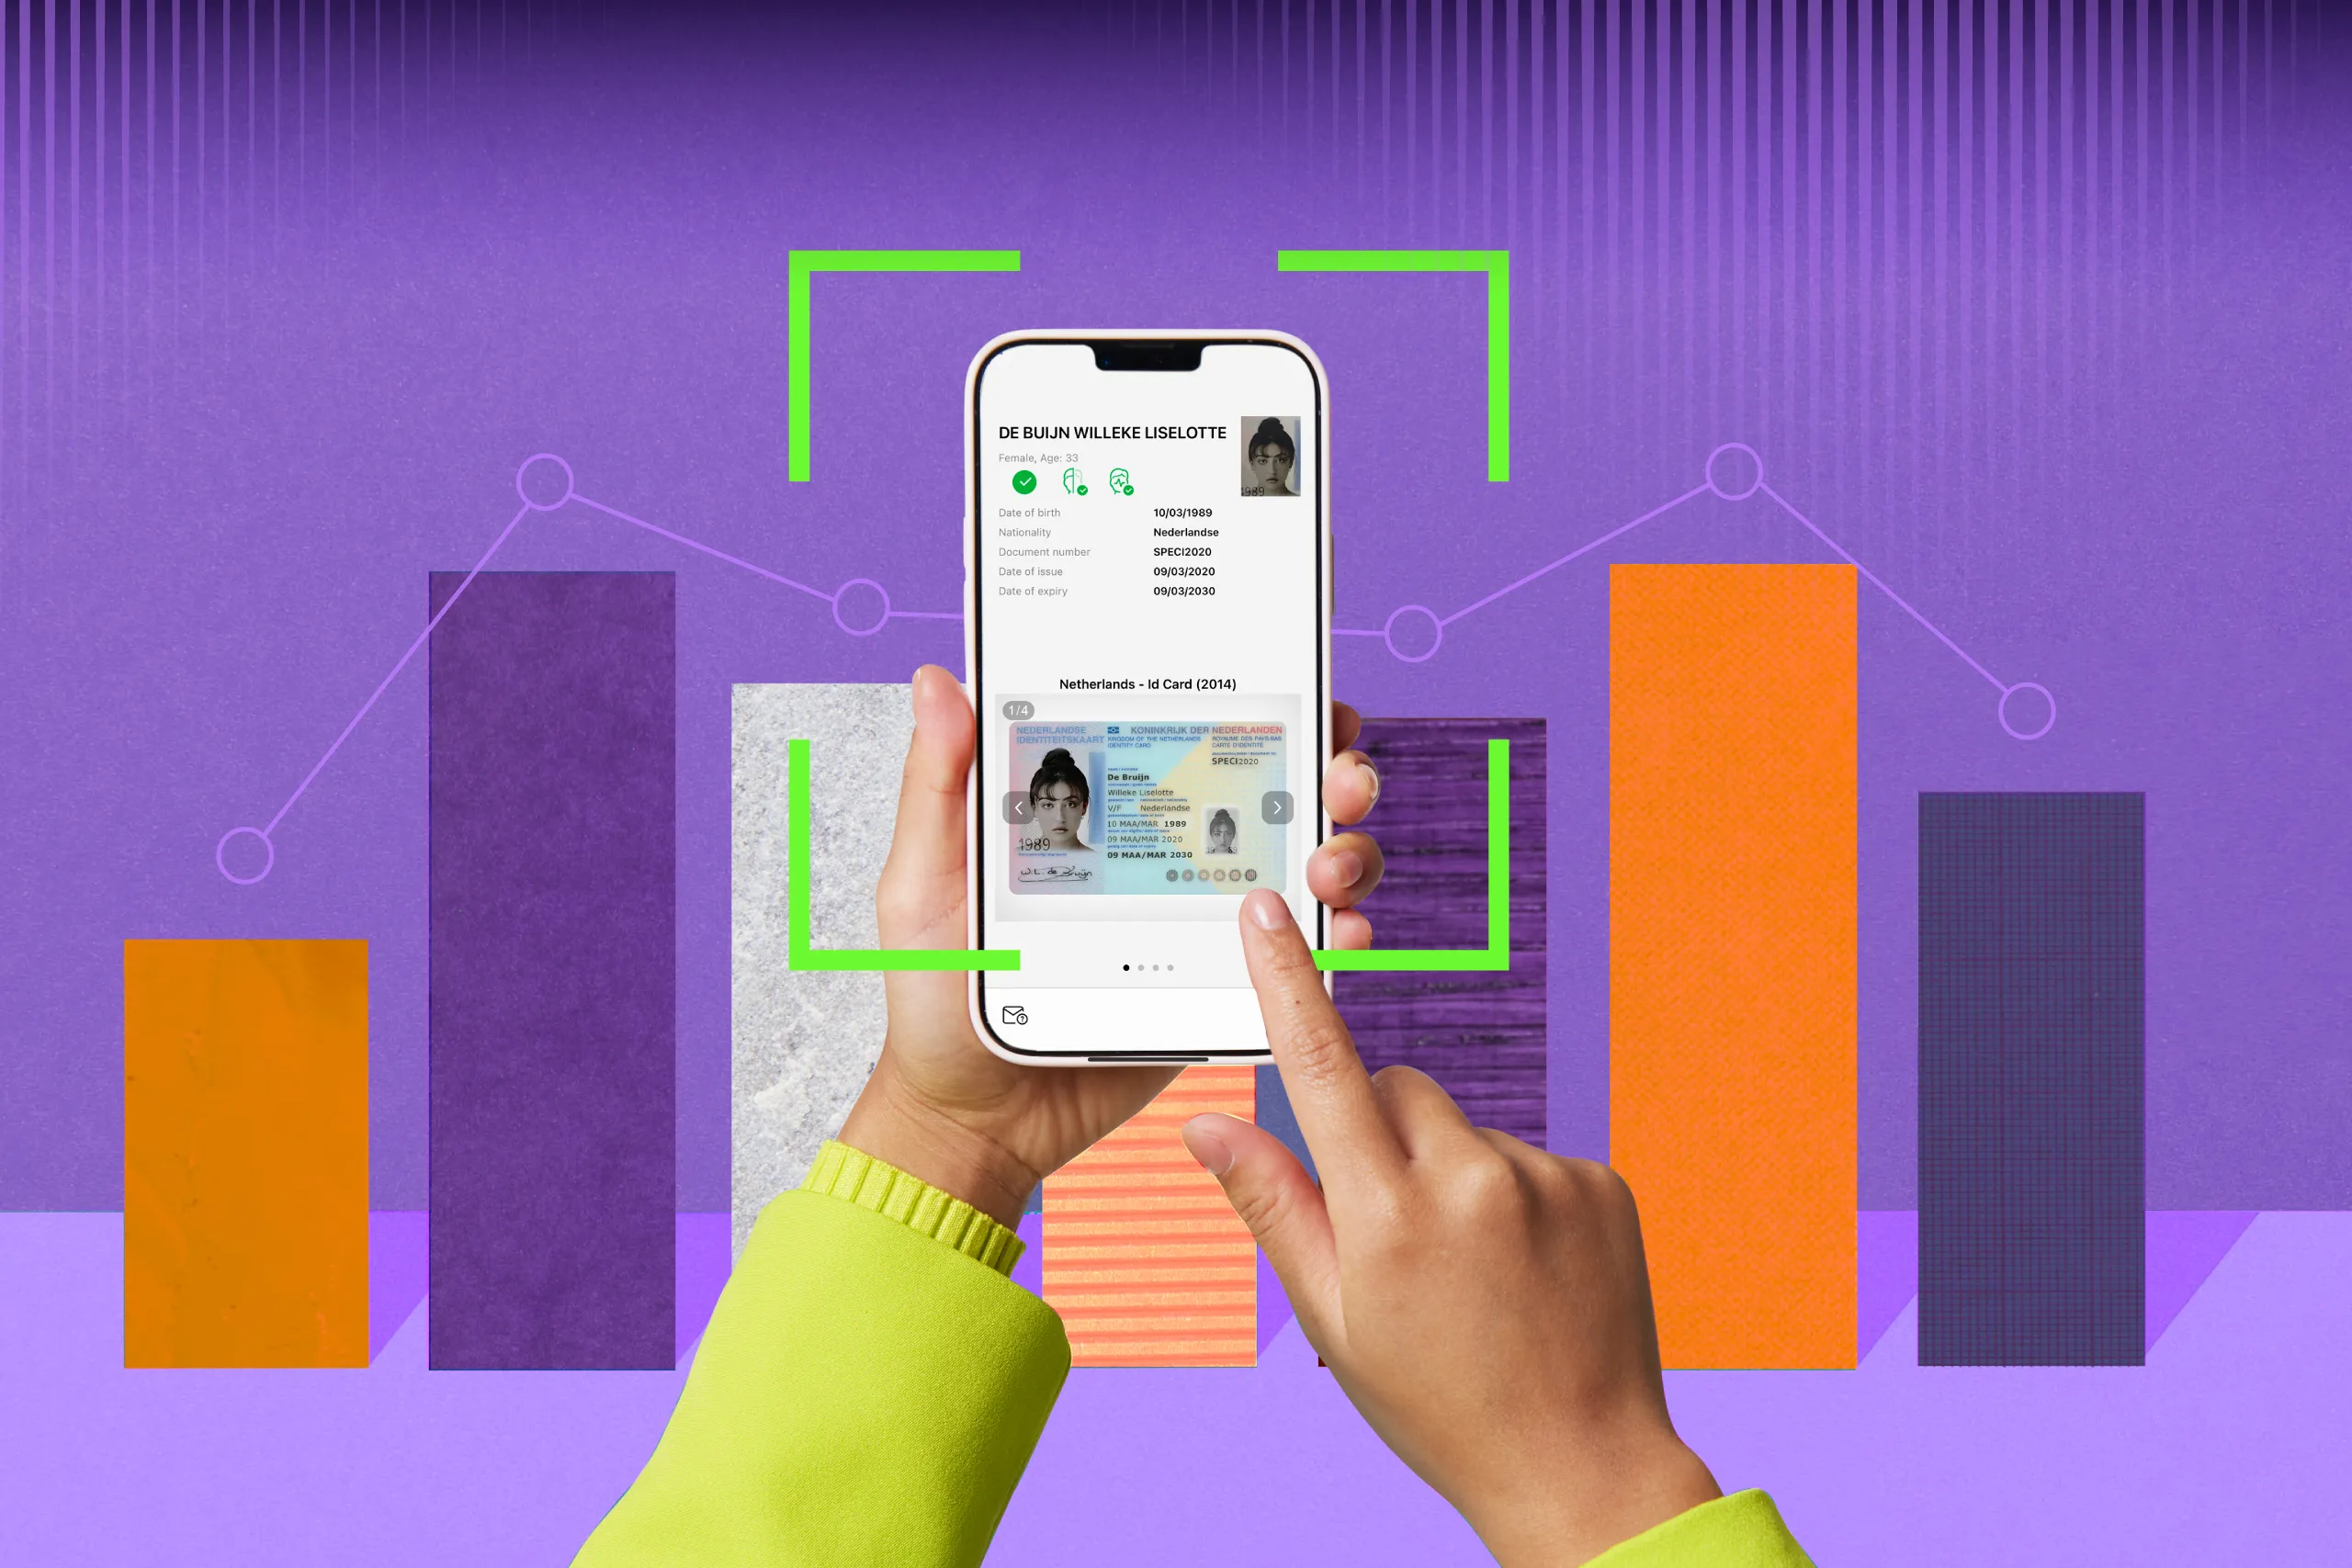
Feature lists can make KYC providers look more similar than they are. Take AML screening, for example. One platform might check sanctions lists during onboarding, while another also monitors changes, sends alerts, and helps compliance teams investigate matches. Both can tick the same box in a comparison table.
To understand what you're actually getting, look closer at five areas:
-
Identity verification coverage and depth. Supporting thousands of identity documents is impressive, but what does "support" actually include? Basic data extraction, document authenticity checks, or RFID chip authentication? Does the support mean only one data page or also a reverse side and additional pages? Ask which verification methods are available for the documents your customers use most. The same applies to biometrics and database checks, whose availability and capabilities may vary by country.
-
KYC and AML scope. Does the platform cover sanctions, PEP, and adverse media screening, KYB, and transaction monitoring? These are separate functions, so check which ones are included, which depend on third-party integrations, and which require additional products. A broad feature list doesn't necessarily mean everything comes in one package.
-
Risk-based workflows and ongoing checks. What happens when a customer needs to be verified again? For example, can a new device or a change in risk level trigger additional identity checks? Can the system refresh customer information or automatically screen existing customers against updated watchlists? Also, distinguish between identity re-verification and ongoing AML monitoring. They address different risks.
-
Case management and auditability. When a check flags a potential issue, what does the compliance analyst actually see? Look for access to verification results, supporting evidence, and previous decisions. The ability to investigate a case, resolve a false positive, and document the outcome matters as much as detecting the issue in the first place.
-
Integration and deployment. How much work will it take to connect the platform to your existing systems? Check available APIs, SDKs, and third-party integrations. Also, clarify who manages the infrastructure and software updates. With vendor-managed SaaS, those responsibilities largely sit with the provider. Customer-managed cloud and on-premises deployments give your team more control, but also more operational work.
One useful test: Ask each vendor to demonstrate a real customer journey, from onboarding to a later risk-triggered check. You'll learn more about the platform's capabilities, limitations, and manual workarounds than from another feature checklist.
Have a complex KYC verification scenario?
Have an identity verification requirement that doesn't fit neatly into a vendor checklist? Perhaps you need to handle unfamiliar identity documents, add an extra layer of assurance to high-stakes KYC processes, or connect verification to a complex existing workflow.
Tell us what you're working on. Our team can help you explore how Regula IDV Platform could handle your requirements, which systems it can work with, and what the implementation might involve.