In brief: Identity verification checks the evidence supporting a person’s identity, and decisioning applies the business’s policy to decide what happens next. Both can involve software or people, and an automated identity check still serves a different purpose from an automated account approval.
How well they work together depends on the checks, the rules applied to the findings, and how the organization handles uncertain cases and measures results.
In July 2025, the UK’s Financial Conduct Authority fined Monzo £21.1 million for failings in its financial crime controls: customers had been able to open accounts using implausible addresses, including Buckingham Palace and 10 Downing Street.
Monzo was comparing applicants’ selfie videos with photo ID, but passing a separate address check was not required for onboarding during much of the period examined. Identity checks provide findings about an applicant, while the surrounding rules determine whether the evidence is sufficient, whether further checks are needed, and whether the application can proceed.
In this article, we will explore where verification ends and decisioning begins, how automated workflows and human review work together, and which metrics help assess their results.
Subscribe to receive a bi-weekly blog digest from Regula
Where does verification end and decisioning begin?
Verification checks the evidence supporting a person’s identity.
Decisioning uses the findings from verification to choose what happens next.
Since the terminology varies across the industry, we use the following working definitions to explain the differences.
Identity verification
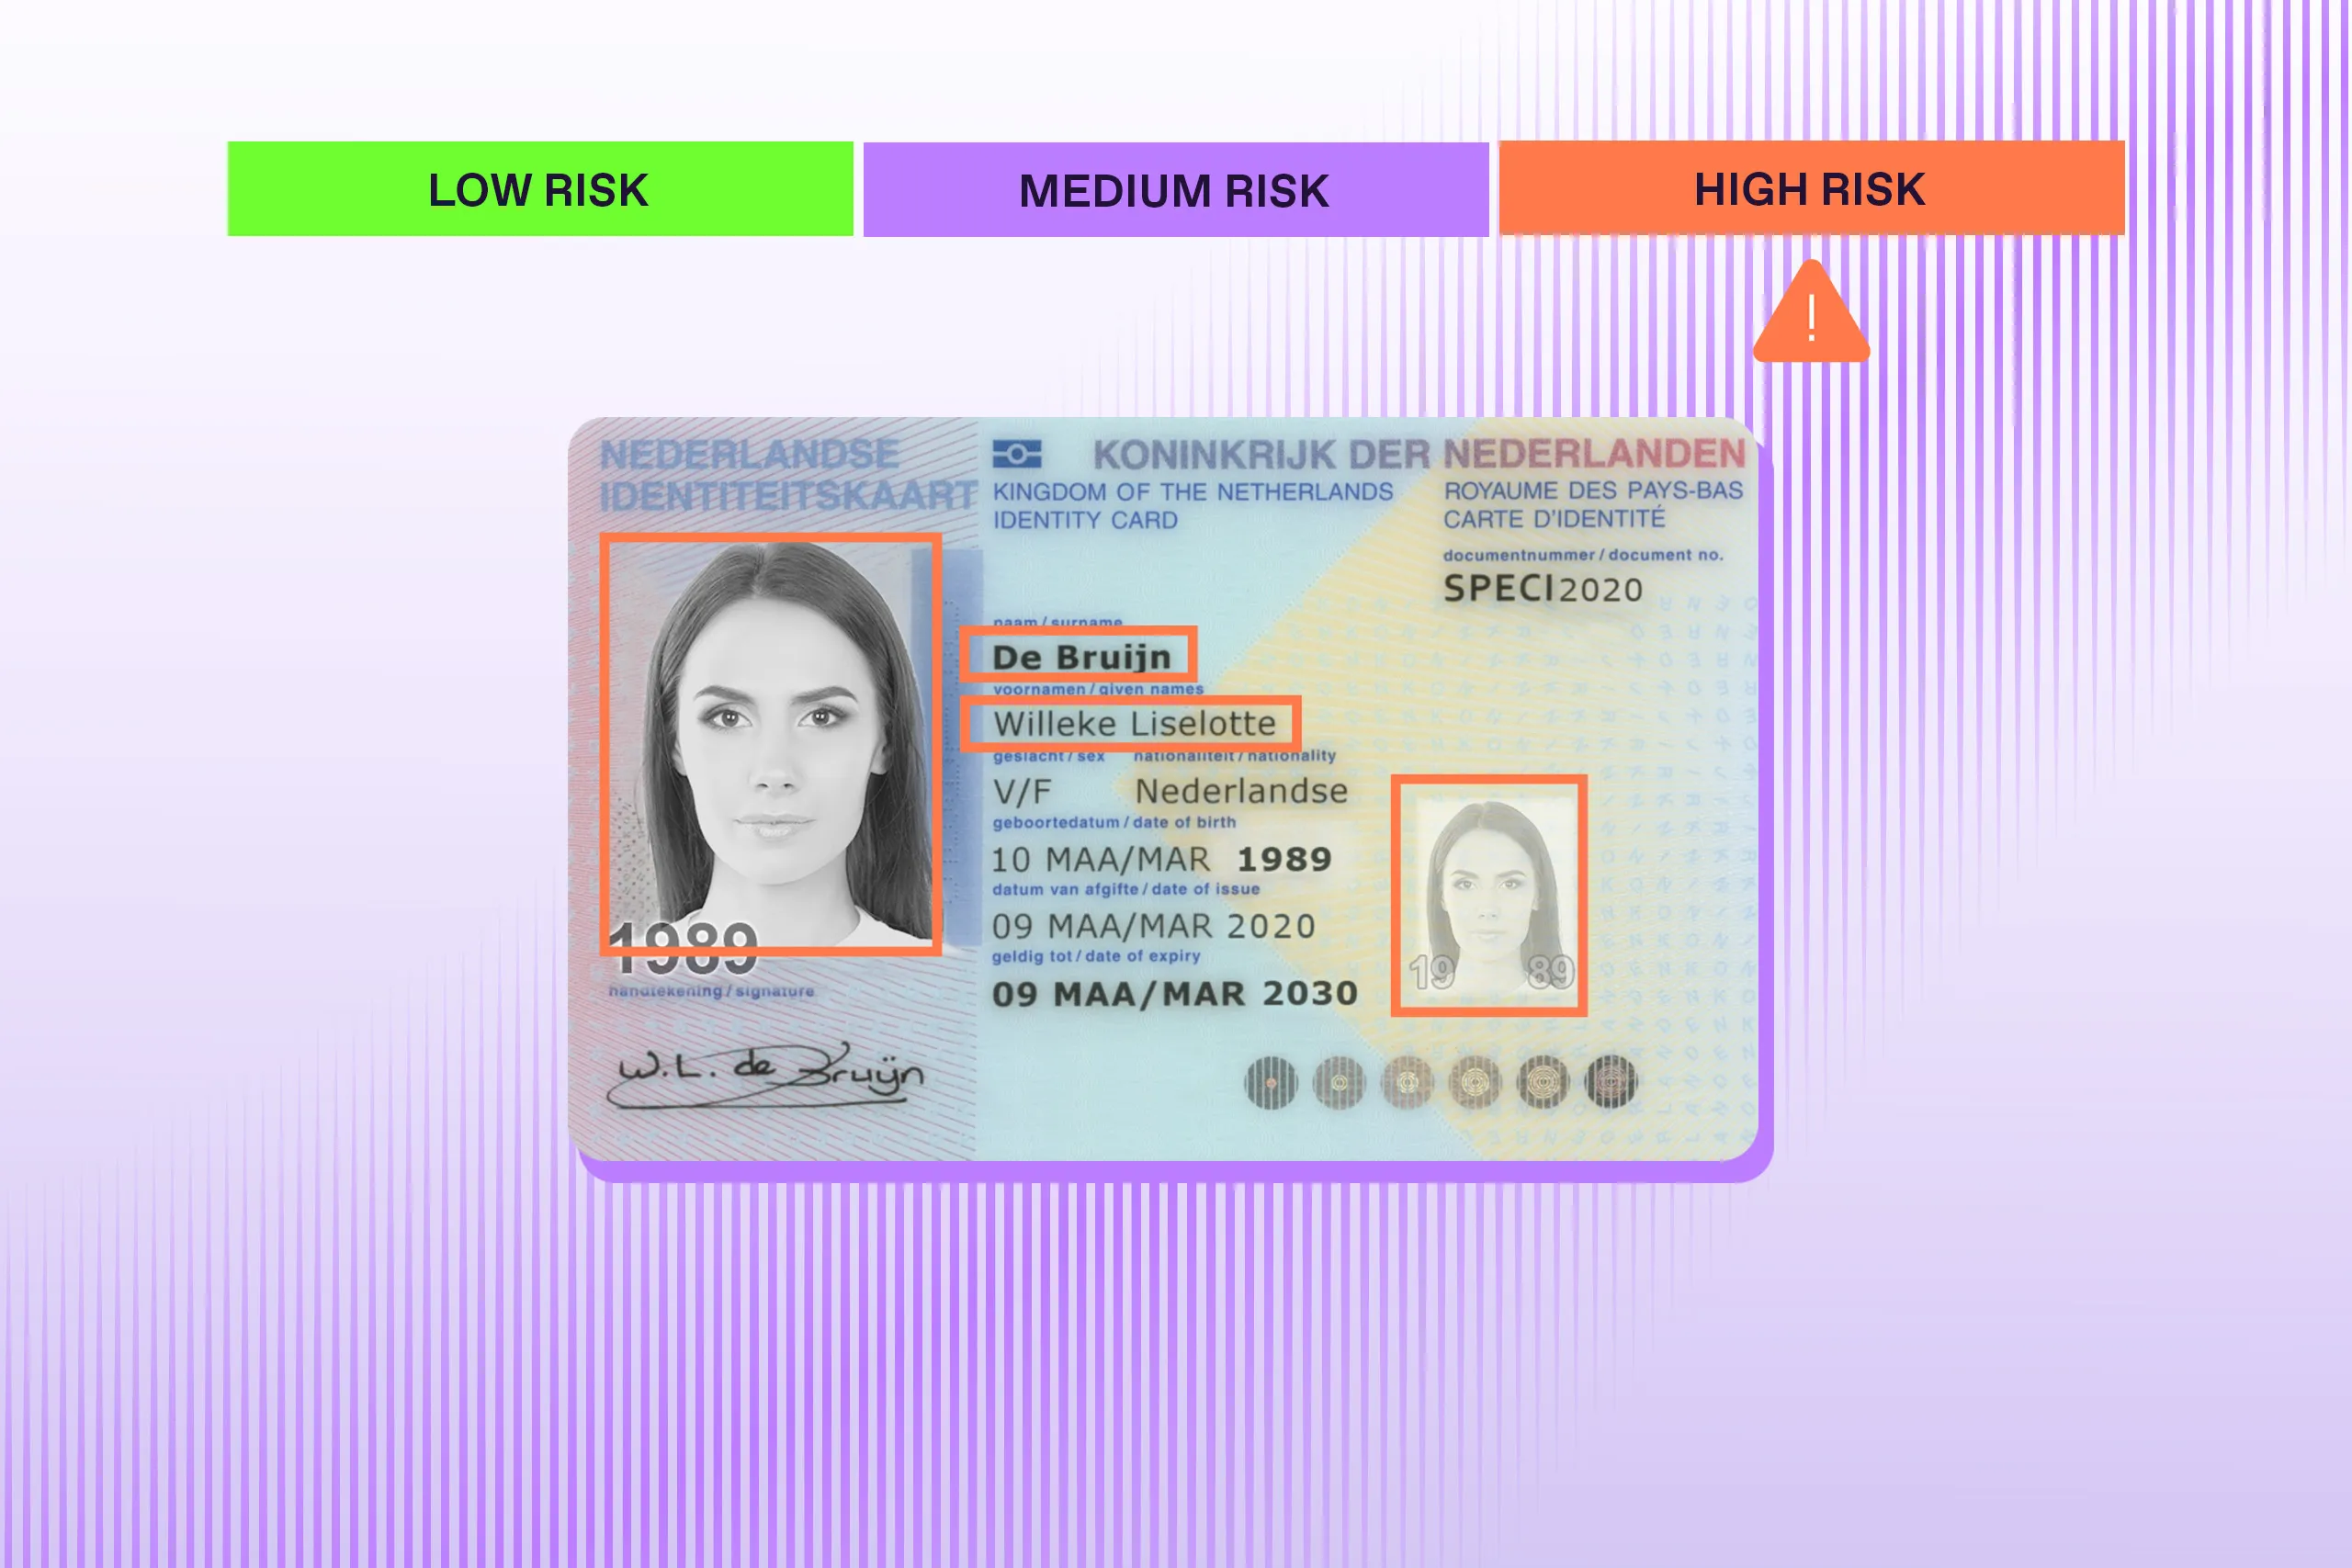
In document-plus-selfie onboarding, identity verification assesses the document’s authenticity and validity and whether the applicant is its genuine holder. It returns the extracted identity details and the results of each check, including any failures or inconclusive findings.
Sanctions screening and checks for politically exposed persons (PEPs) may also run alongside identity verification as part of the business’s wider customer due diligence and anti-money laundering (AML) controls.
Workflow decisioning
Workflow rules use those findings to choose the next step: poor image quality may prompt another capture, while a mismatch may lead to further checks or human review.
These rules also define when the verification requirements have been met and the application can move on.
Business decisioning
A business (e.g., a bank) uses the findings alongside its other requirements to decide whether to approve the customer and allow a certain action (e.g., open an account). It's worth noting that a customer may pass identity verification but still fail to meet the account’s residency requirements, for instance; so the verification result and account-opening decision can differ.
In practice, a workflow may also include the account-opening rules, so routing a case and approving an account can happen in the same system. Both types of decision can be automated or involve human review, depending on how the business has designed the process. Following rules set by people still counts as automated decisioning when software selects the outcome.
How does verification become a business decision?
The workflow below shows how checks and decisions fit together once a business has defined its evidence requirements and acceptance rules.
| Step | What happens | Function |
|---|---|---|
| 1 | The applicant submits a document, a selfie, and the required identity information | Evidence collection |
| 2 | Capture checks assess whether the document and selfie images are usable | Identity verification |
| 3 | Workflow rules determine whether to continue or request another capture | Workflow decisioning |
| 4 | Document checks extract identity details and assess authenticity, validity, and data consistency | Identity verification |
| 5 | Face matching compares the applicant with the document portrait, and liveness checks assess live presence | Identity verification |
| 6 | The check results are returned, including any failed, incomplete, or inconclusive checks | Identity verification |
| 7 | Workflow rules select the next step: assess the application, request more evidence, or send it for human review | Workflow decisioning |
| 8 | The business applies its acceptance rules to verification findings and other relevant information to approve or decline the application | Business decisioning |
| 9 | The receiving system applies the outcome and records the supporting evidence and policy | Action and recordkeeping |
Note: Cases may return to earlier checks or end sooner, depending on the findings and acceptance rules.
When should identity decisions be automated or reviewed?
Straightforward applications can often be handled automatically because the evidence is clear and the business has already defined the response.
Human review is more fitting when someone can investigate a mismatch, gather more information, or approve an exception allowed by the policy.
| Situation | Possible handling |
|---|---|
| Required checks are complete and the applicant meets the business’s acceptance rules | The application can proceed automatically under the approved policy |
| Reliable evidence shows that the applicant is ineligible | An automatic decline may be appropriate when the policy and applicable law allow it |
| A required check is incomplete or inconclusive | Another attempt, additional evidence, or an approved fallback may resolve the case |
| Findings conflict or relevant concerns remain unresolved | The case can be sent to an authorized reviewer to investigate the issue or assess a policy exception |
Automation applies the rules it’s given consistently, so a poorly chosen document requirement or threshold can affect every application it touches. Testing changes against cases that reflect the business’s customers helps show their likely effect before the rules go live.
The response can also reflect what’s at stake and how easily an error can be corrected. A payment that would be difficult to recover may justify stronger verification, a temporary hold, or a second approval. Manual review can also be slow or inconsistent, so it benefits from the same monitoring as automated decisions.
What does human control involve?
People can control an automated process by defining its rules and thresholds, approving changes, and deciding how exceptions are handled. This often helps to reduce repetitive work, while there is still total control over who gets accepted and who is responsible for each decision.
Rules, permissions, and required steps
A record of the evidence, relevant external data, and the versions of rules or models used helps explain why a case received a particular outcome. It also makes it easier to investigate changes in results after a threshold or screening source is updated.
Important process controls include:
-
Clear permissions for changing rules, thresholds, and accepted evidence
-
Required checks that must be completed or handled through an approved alternative before a case proceeds
-
Clear responsibility for review and escalation, including who can approve exceptions
-
A history of policy changes, reviewer actions, and reasons for overrides
These controls help keep required steps in place when several systems and people contribute to a case. An application can remain on hold until an investigation is complete, with the reason recorded when an alert is cleared.
The rules also need to account for checks that use the same source data, because their findings may overlap. In that case, another passing result may add little new evidence.
Case management for human review
Conflicting information, signs of fraud, or unresolved screening alerts may need investigation. Case management brings the evidence together and helps people keep track of who handles the case and what happens next.
Different review arrangements serve different purposes:
-
Case ownership gives someone responsibility for investigating the issue, requesting evidence, and resolving the case or passing it to an authorized colleague
-
Maker/checker, or the four-eyes approach, requires a second authorized person to independently review and approve a specified action, such as a policy exception or a sensitive rule change
-
Reconsideration allows a reviewer to assess new evidence or a challenge to an earlier decision
Keeping a record of the evidence and reasoning helps the next reviewer understand what happened, including why a decision was upheld or changed.
For example, Regula IDV Platform connects automated verification workflows with case management. Reviewers can access document and biometric check results, related sessions, and fraud indicators together, helping them investigate the issue and choose the next step. Meanwhile, actions and their reasons are recorded for later review.
And while established organizations may already have workflows in place, growing businesses may need help defining them. That’s why Regula’s Professional Services team can also help document the process, configure the workflow, and support launch, followed by an agreed period of closer support called hypercare.
Product and project managers can work with operations, compliance, and engineering on the setup, even without a dedicated fraud team. The business defines who handles each outcome and how verification findings feed into its acceptance decisions.
WORTH NOTING | Responsibility for an automated outcome
Software can select an outcome while the business remains accountable for using it.
Under FATF standards, a financial institution remains ultimately responsible for customer due diligence when it relies on another regulated entity to carry out permitted checks. Providers may also have duties under applicable law and their contracts. Who makes a decision and who is accountable for it are separate questions.
What do verification and decisioning workflows look like in practice?
Note: The following examples illustrate policy choices. The exact requirements depend on the product, jurisdiction, and level of risk the business accepts.
Banking: account onboarding
A bank can use identity findings alongside screening results and the requirements for the selected account. That allows different routes through the same workflow:
-
Automatic progression when the required checks are complete, acceptance rules are met, and relevant screening concerns are resolved
-
Case review when a possible watchlist match or conflicting information needs investigation
Those identity findings can also be useful if the customer applies for another product, with further checks where needed to keep the information current.
Marketplaces: changing a payout destination
When someone recovers an account and then changes where payouts are sent, the marketplace may need to check who controls the account.
Depending on the policy, the response can include:
-
Holding the requested change while fresh verification is completed
-
Looking at how the account was recovered, the new payout destination, and relevant account activity alongside the identity findings
-
Allowing the change when the policy conditions are satisfied, or referring unresolved concerns to an authorized reviewer
Face matching with Regula Face SDK, for example, could help check whether the person matches the account holder’s reference image. And the wider process will then determine whether the payout change can go ahead, given how the account was recovered and what has happened since.
Which metrics show whether verification and decisioning work?
Verification metrics show how reliably the system checks identity evidence.
To assess decisioning, the business also needs to know whether approved applications turn out to be fraudulent and whether eligible people are turned away.
Lastly, completion and review metrics help connect the two by showing where customers struggle or cases slow down.
| Part of the process | Useful metrics |
|---|---|
| Identity checks | False acceptance and rejection rates (FAR/FRR), face-comparison error rates, document and liveness error rates |
| Business outcomes | Confirmed fraud after approval, fraud losses, eligible applicants incorrectly declined, review and appeal outcomes |
| Completion and review | Completion and abandonment rates, retries, time to a final result, share of cases sent to review, and time to resolve them |
All these metrics are interconnected in a way that it's nearly impossible to have each one at its perfect value. When the priority is to improve one set of metrics, another can often suffer; so it's important to balance them well. For example, a stricter face-match threshold may reduce false matches, but at the same time it may cause more genuine customers to fail the check and drop off.
A proof of concept can test these trade-offs using the documents, devices, and capture conditions the business expects to encounter. Recording which checks and test data produced each error rate makes the results easier to interpret.
Monitoring continues after a decision, since fraud may become apparent only after approval. Looking into those cases helps separate identity-check failures from problems in acceptance rules or other controls. Complaints and reviews of declined applications can also reveal eligible customers who were turned away.
Keeping automation under business control with Regula
Reliable checks and clear rules make it easier to automate routine cases and identify those that need more attention. The aim is to automate where the evidence and policy support a clear response, with further checks or human review where they can help resolve uncertainty. Monitoring the results then helps the business adjust both its verification settings and its acceptance rules over time.
Regula IDV Platform brings identity checks, configurable workflows, risk-based rules, and case management together. Workflows can trigger additional checks and automatically create cases for human investigation. Persistent identity profiles and audit trails keep the findings and review history connected across verification sessions.
With on-premises and cloud deployment options, plus integration with existing business systems and third-party services, Regula supports these processes within the organization’s established acceptance procedures.
Talk to the Regula team about configuring verification workflows around your business’s checks, review procedures, and acceptance rules.